

Event Summary: October 2026 Forum for Housing Executives East
October 12-13, 2026, Lafayette Hill, PA
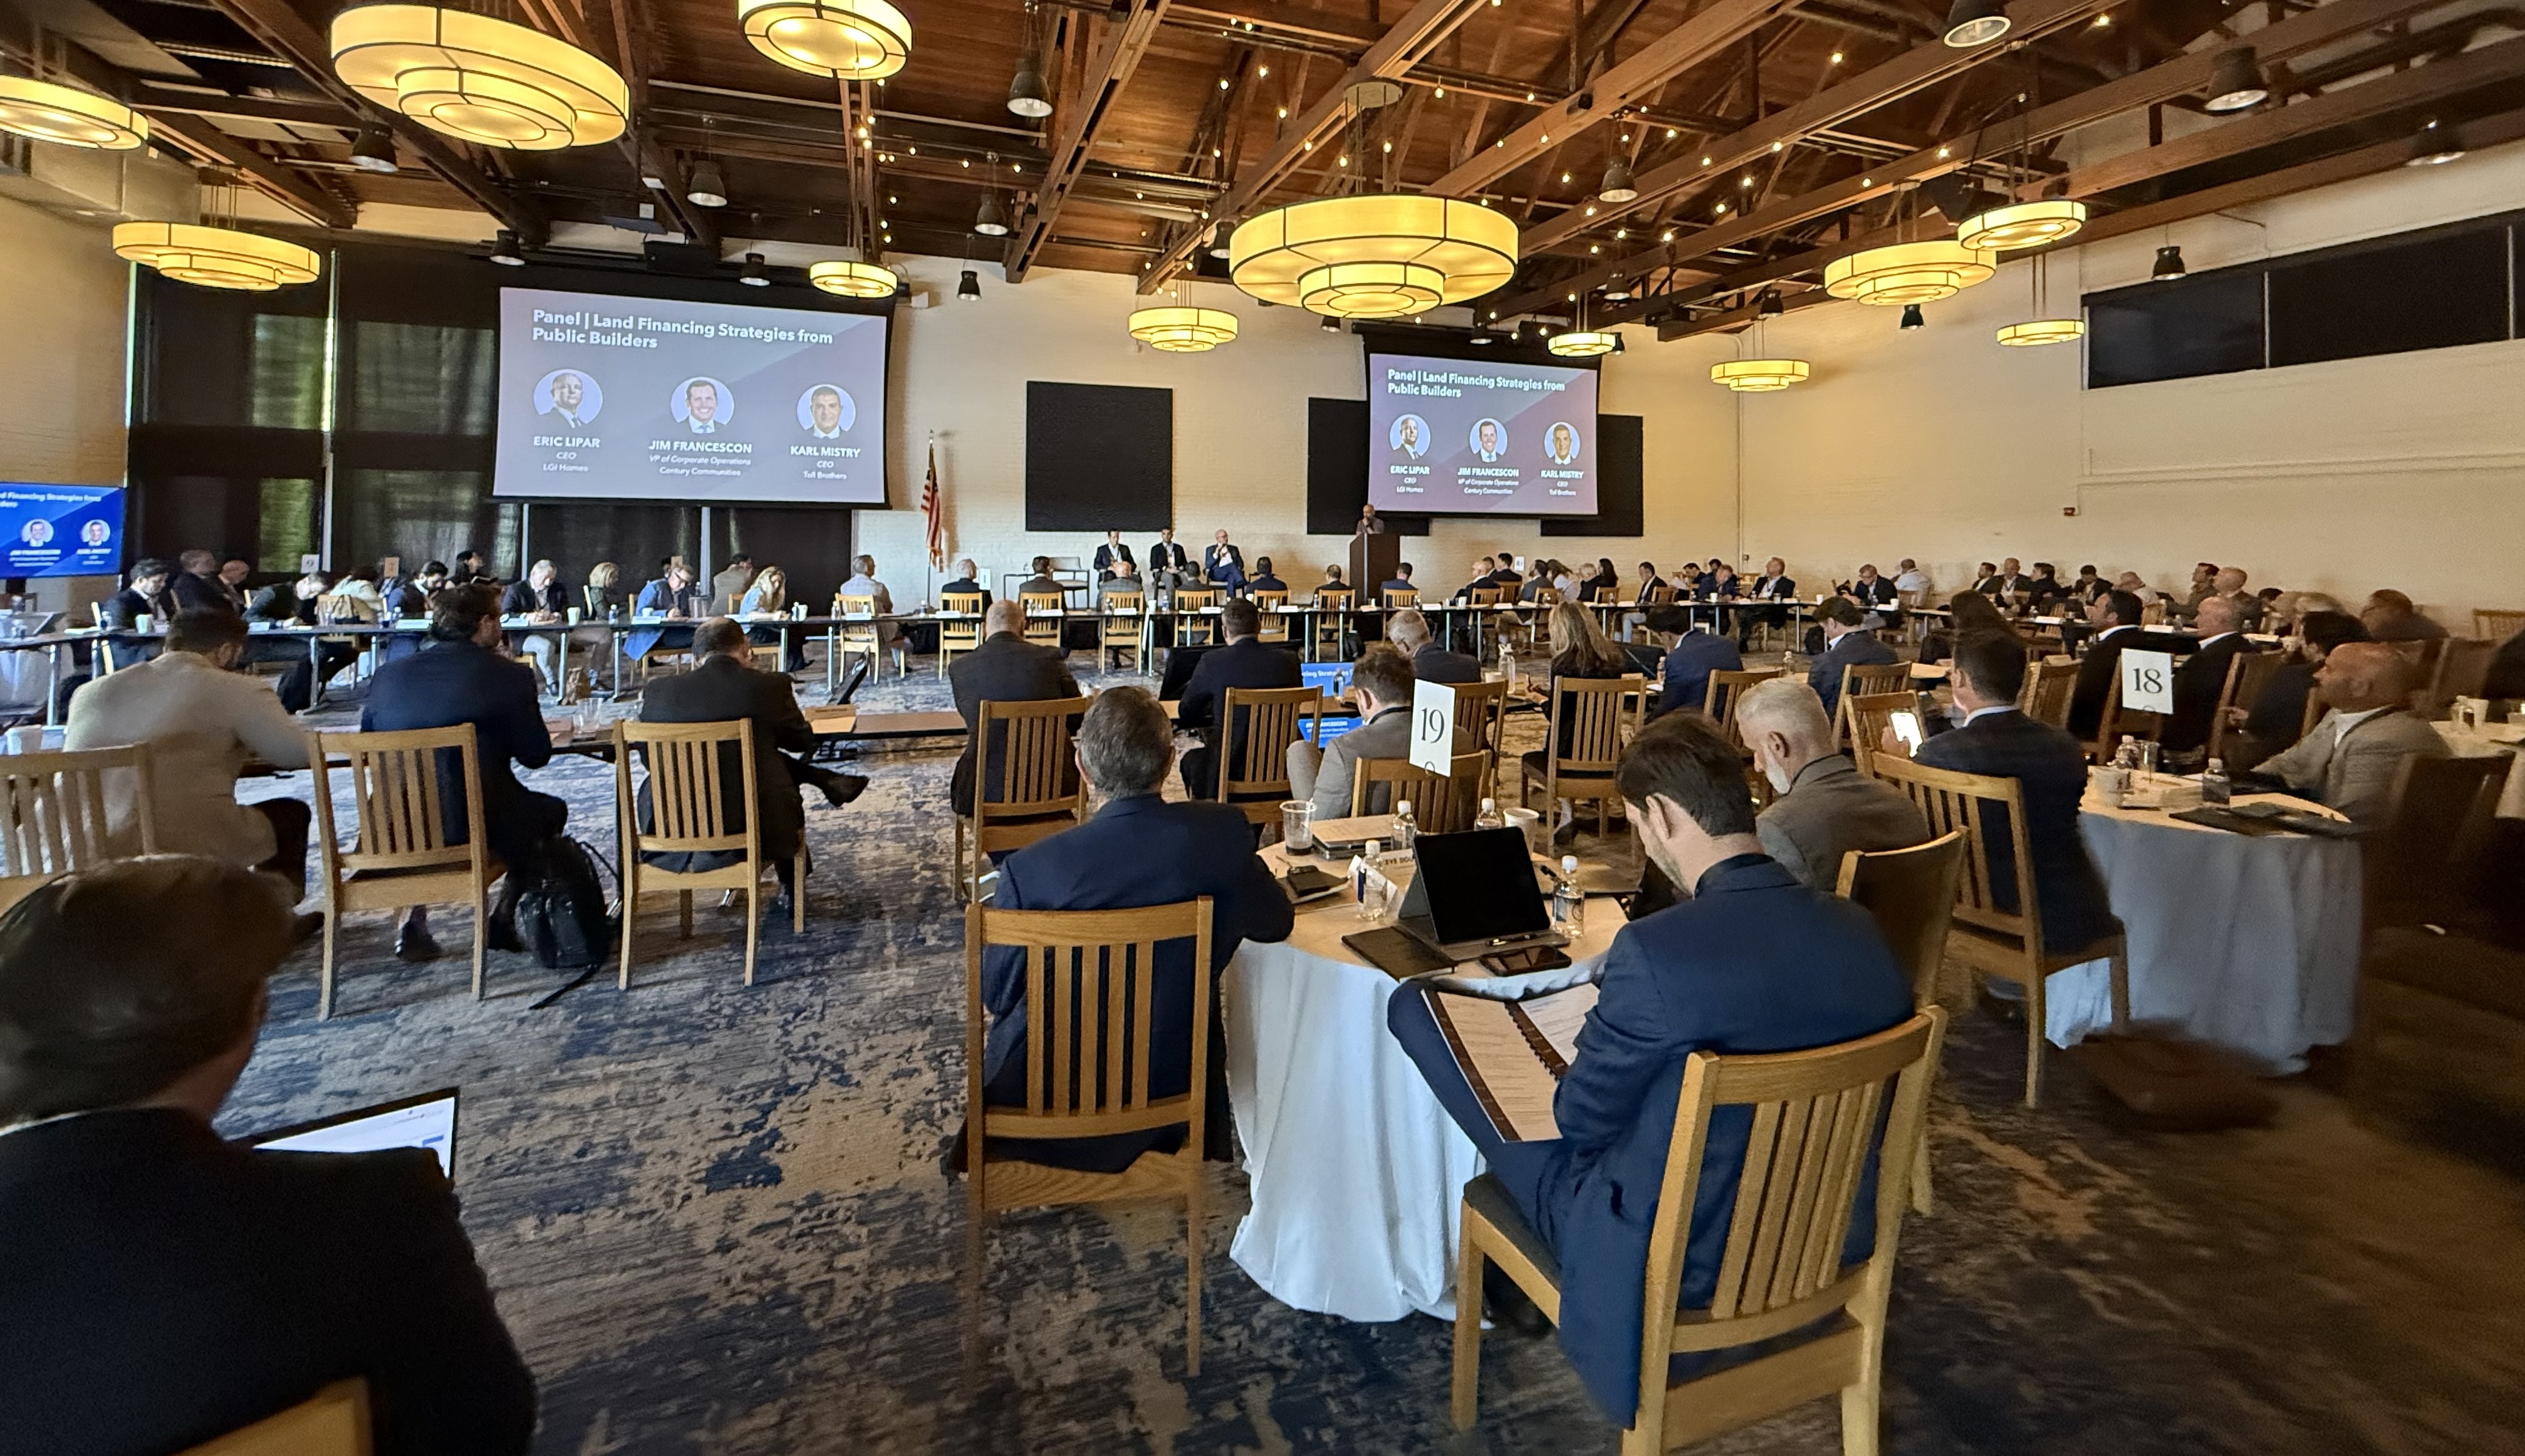
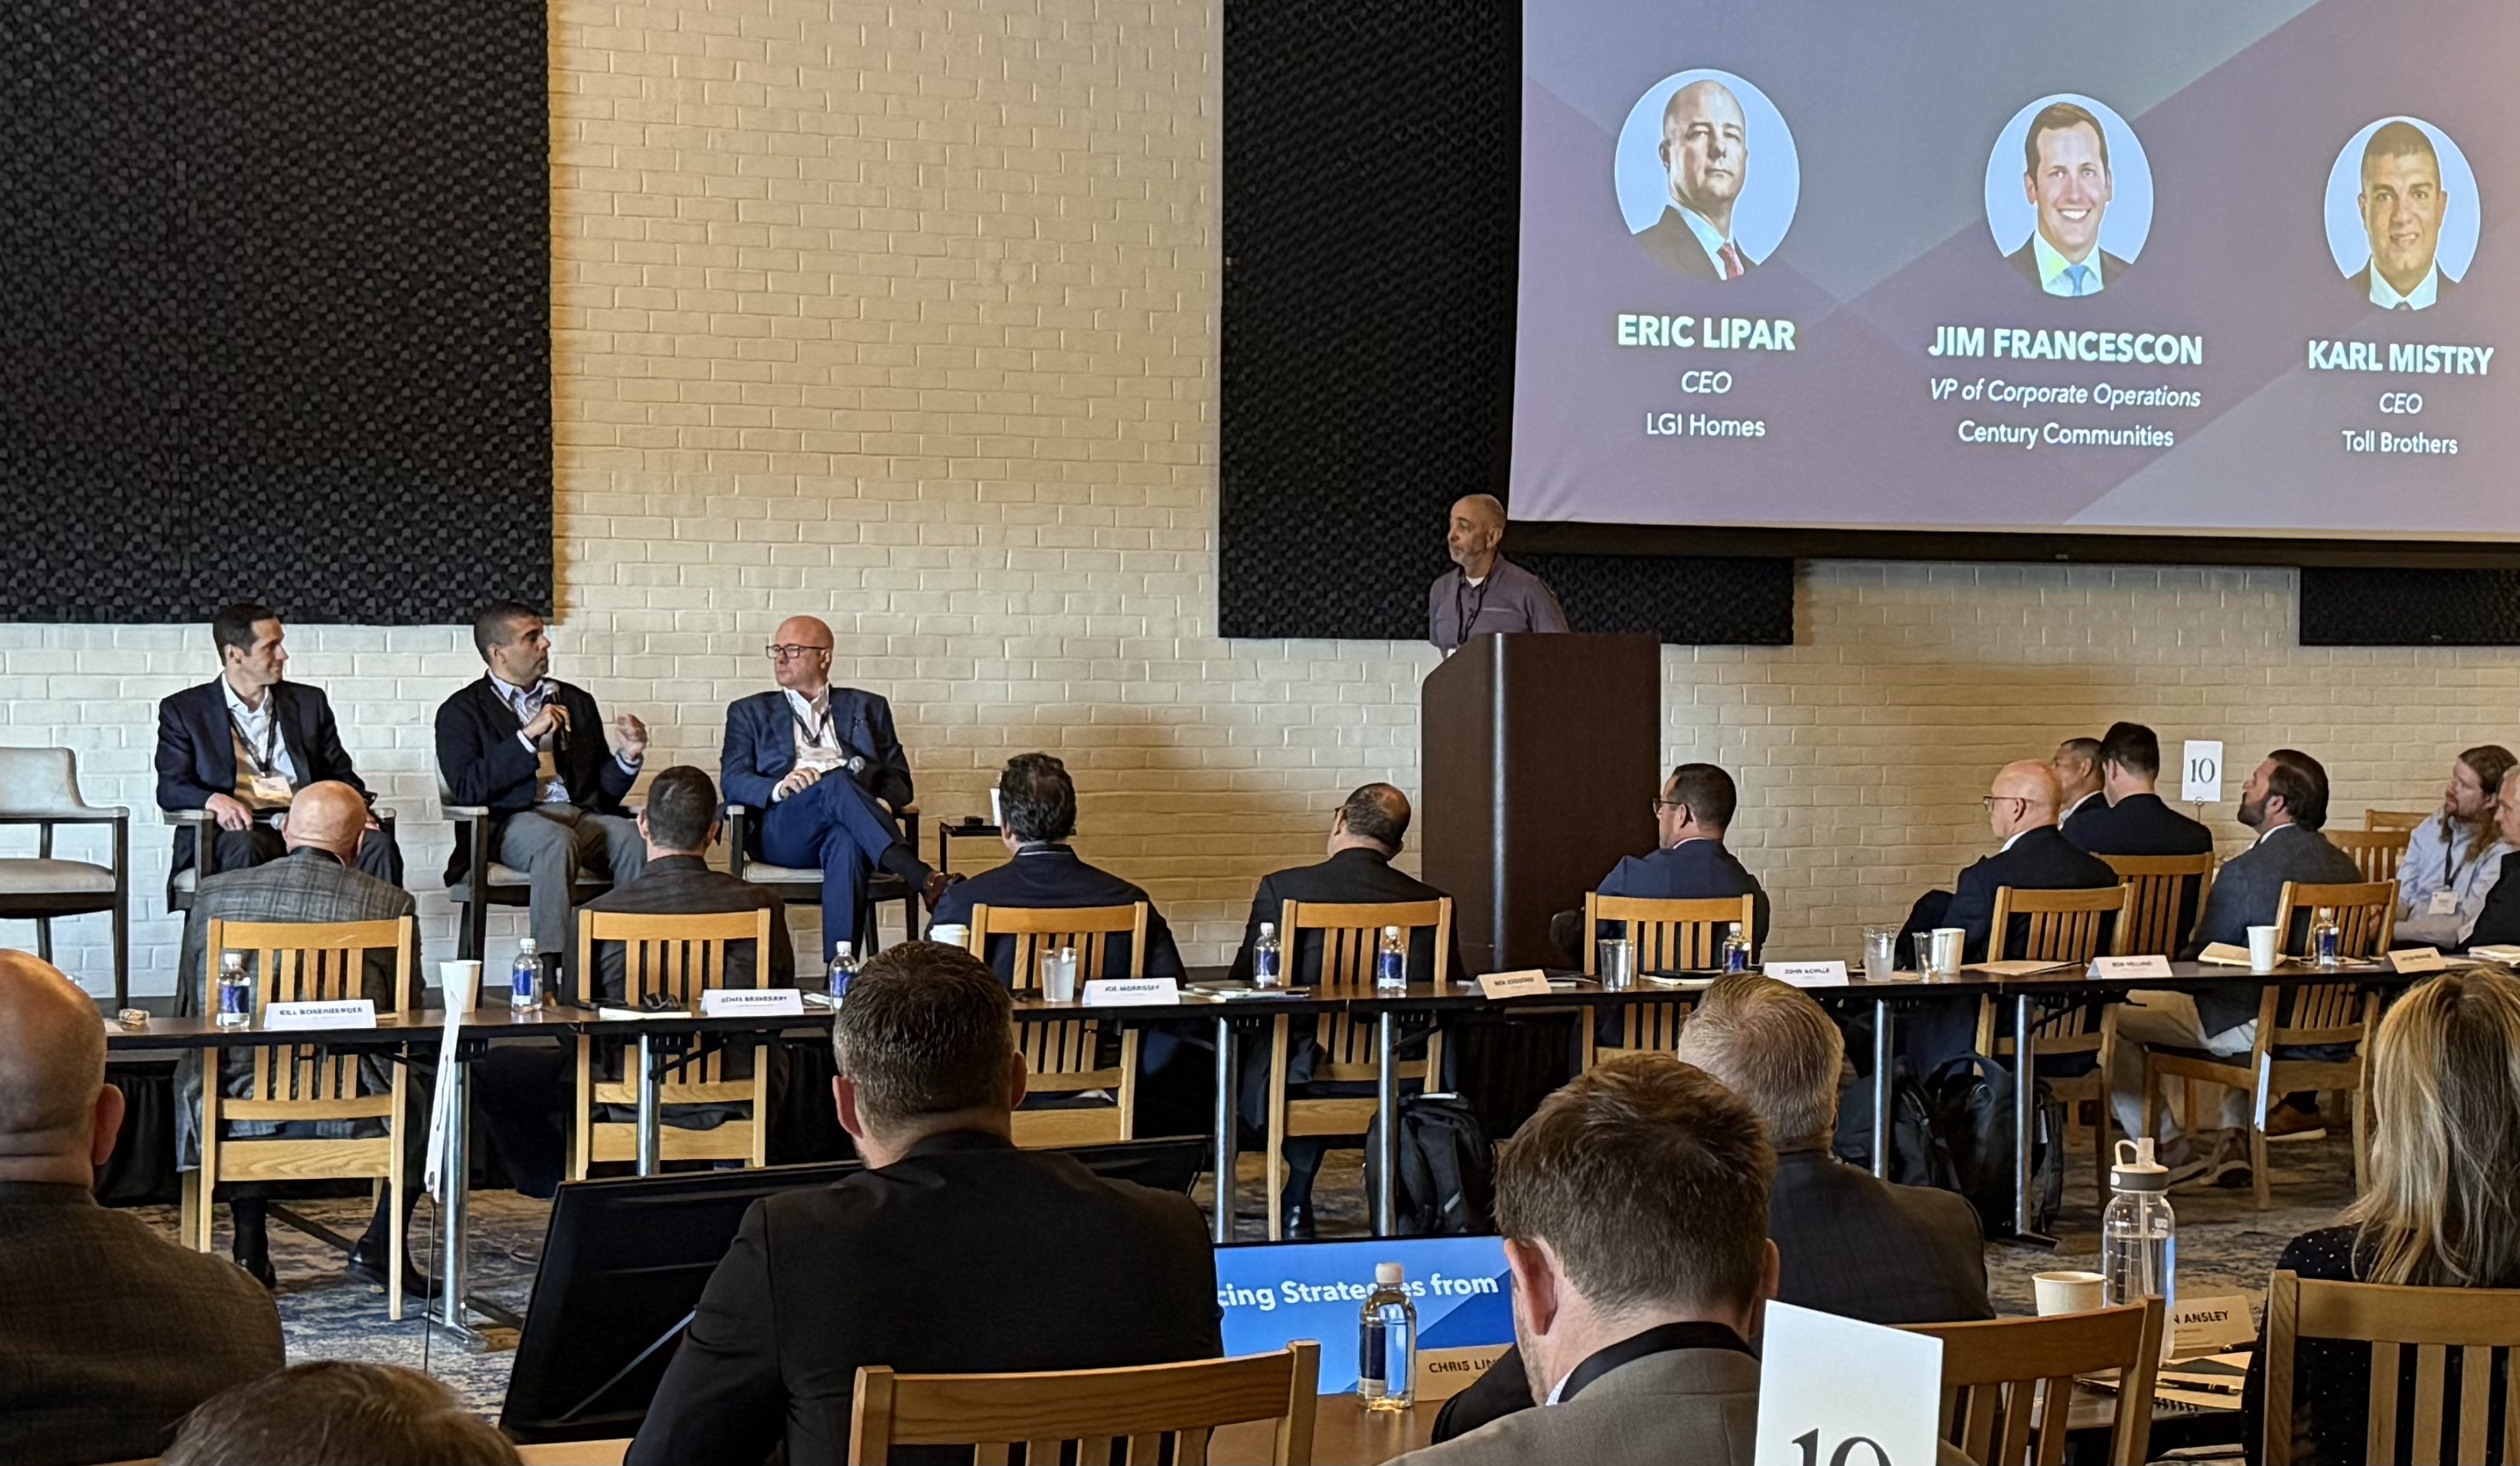
On October 13, Builder Advisor Group, Avila Real Estate Capital, and Pacific InterWest hosted the Forum for Housing Executives in Lafayette Hill, PA — the first East Coast edition of the annual forum. The event brought together the nation’s top builders and developers. Sessions covered capital markets and M&A, Japanese investment in U.S. homebuilding, changing household needs, applications of AI, public and private builder strategies, and the industry outlook. The forum includes builders that represent close to half of all new single-family home deliveries in the United States.
Highlights and Key Takeaways
· Macro & rates: Approximately $10 trillion in Treasuries must be refinanced within 12 months as foreign holdings of U.S. debt decline; the 30-year mortgage rate could track toward 7.25% if the 10-year Treasury holds at 5.5%.
· Affordability: Affordability remains a structural challenge involving land costs, impact fees, zoning, construction costs and a mismatch between available homes and household needs—not just mortgage rates.
· Market outlook: Net new-home prices down approximately 3% year over year after incentives, with the Midwest showing positive net price appreciation; higher rates and strained affordability are expected to persist through 2026–27.
· Builder margins: Public-builder gross margins are at approximately 20%, down from approximately 26% at their Q4 2022 peak; incentives of approximately 8–12% of home price, versus 2–3% in 2021.
· Private builders: Median private-builder gross margins fell from approximately 20% in 2024 to 18% in 2025, with ROE down from approximately 17% to 6% and debt-to-capital up from approximately 52% to 62%.
· M&A: 12 announced homebuilder deals in 2026, compared with 17 in all of 2025. Japanese-backed builders accounted for approximately five of the 2026 transactions.
· Japanese capital: Daiwa House, Sekisui House and Sumitomo Forestry described different approaches to operating their U.S. builders, ranging from relatively autonomous brands to a consolidated platform.
· Capital & land: New investment-grade issuance priced at approximately 5.1% coupons versus 7.2% for high yield; rising land impairments indicate new deals are difficult to underwrite at current margins and absorptions.
· Consumer preferences: Willingness to buy a smaller home doubled from ~20% to ~40% in two years, and buyers will accept a smaller yard but still want one. Location is the first trade-off: 41.1% said a home in their preferred location was too expensive.
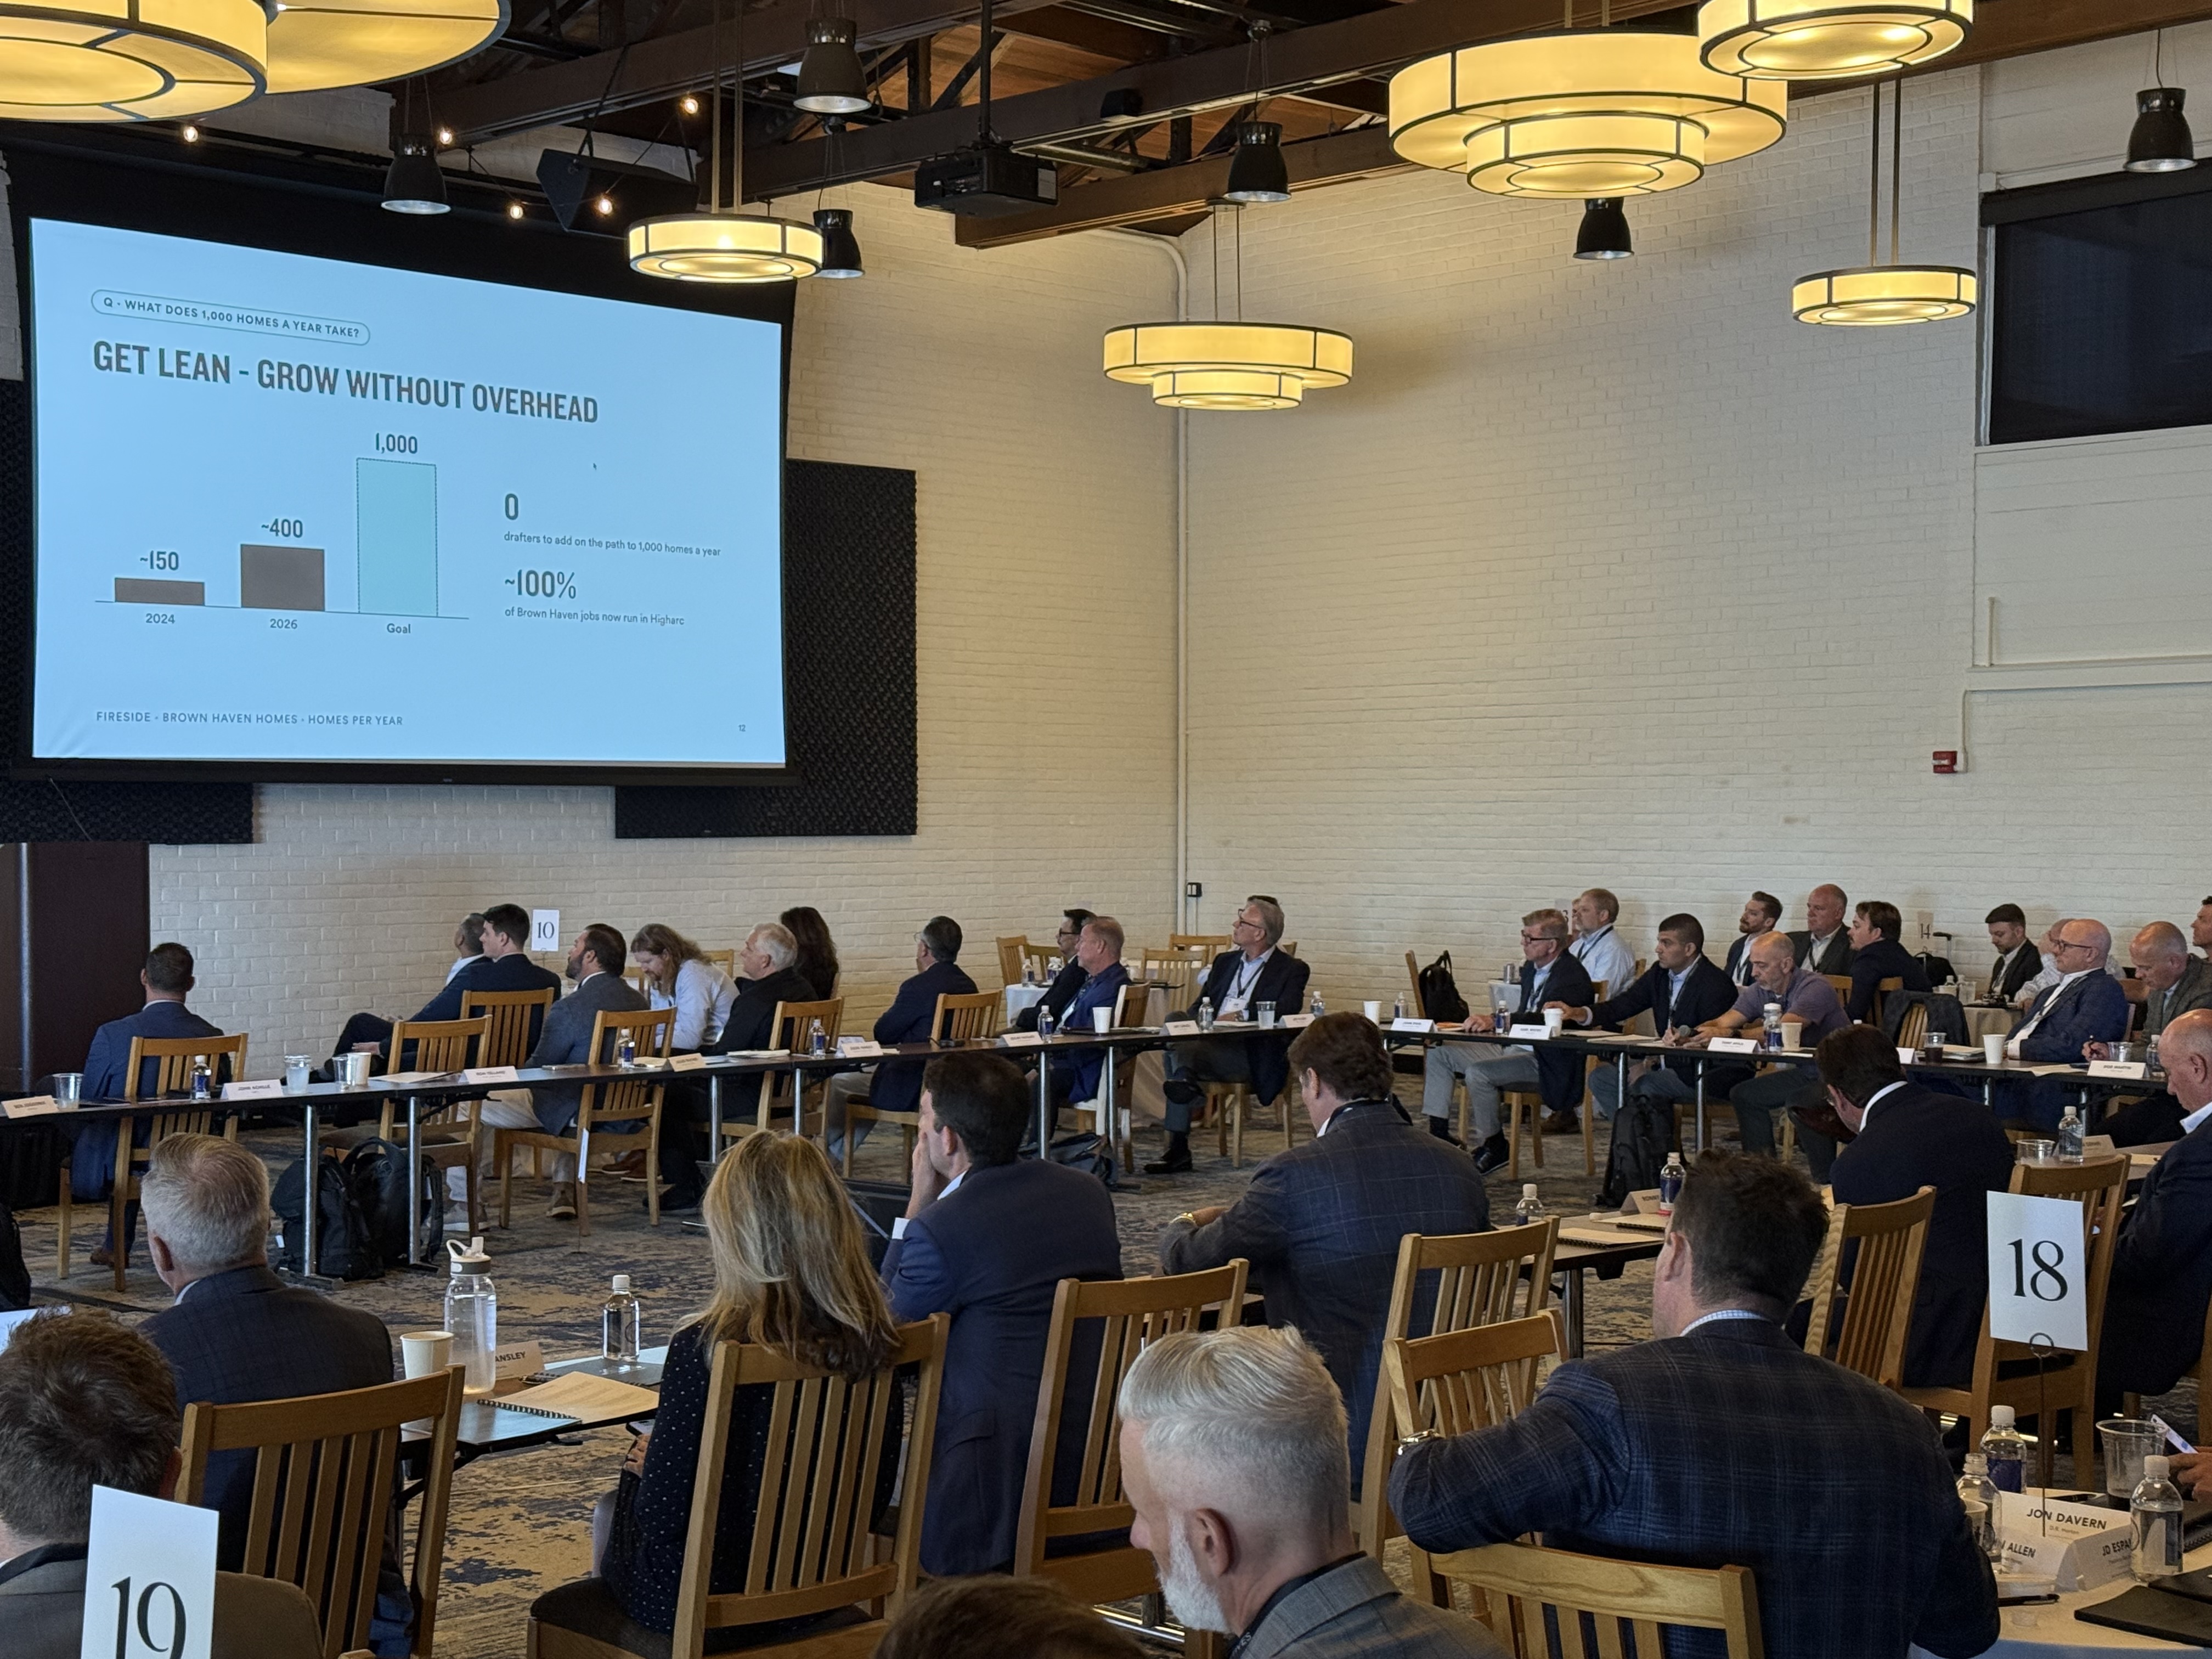
· AI & operations: Sessions covered connected design and construction data, purchasing analysis, trade-company automation and AI-native homebuilding. Panelists emphasized operational outcomes rather than AI adoption for its own sake.
· Builder strategy: Public and private builders described different responses to slower demand: protecting price or margin, adjusting speculative inventory, underwriting land to current conditions, and differentiating through product and location.

EVENT GALLERY